Caribou Biosciences at a Crossroads: CRISPR Pioneer Navigates Financial Storm as Clinical Pipeline Stalls
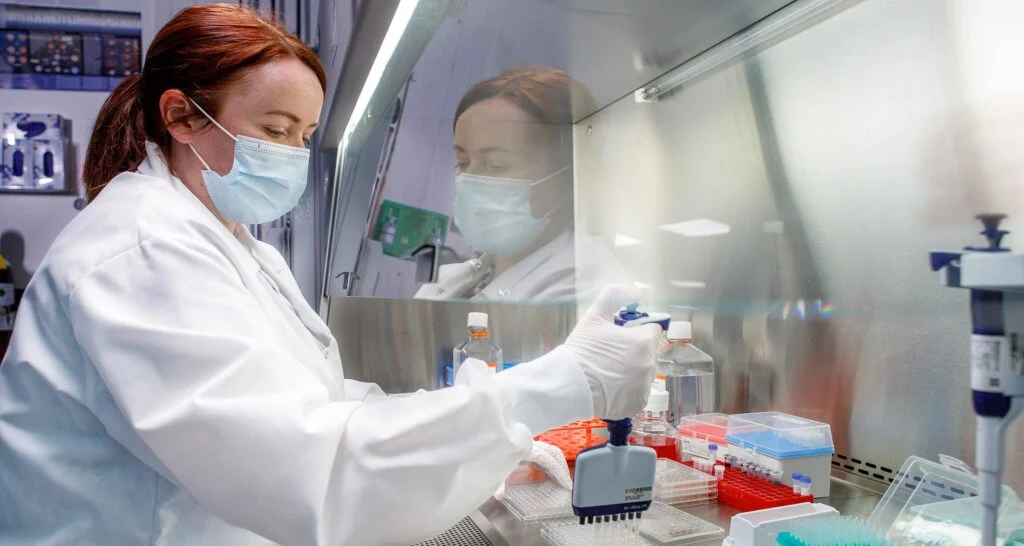
In a development that has sent shockwaves through the biotech sector, Caribou Biosciences (Nasdaq: CRBU)—the Berkeley-based genome-editing powerhouse co-founded by Nobel laureate Jennifer Doudna—has officially announced its intent to explore "strategic alternatives." This pivot follows a devastating week for the company’s shareholders, during which the stock plummeted 62%, culminating in an 83% decline over the trailing twelve-month period.
The announcement marks a sobering inflection point for one of the industry’s most high-profile CRISPR entities. Facing a harsh capital market environment and intensifying competition from established pharmaceutical giants, Caribou is now signaling a retreat from its ambitious clinical-stage pipeline. The company has confirmed an "unspecified" but "substantial" reduction in its workforce and a total halt to trials for its two flagship allogeneic chimeric antigen receptor (CAR) T-cell therapy candidates.
The Chronology of a Crisis
To understand the current volatility, one must look back at the company’s trajectory. Founded in 2011, Caribou emerged from the pioneering work of Jennifer Doudna, Martin Jinek, and James Berger. It quickly established itself as a standard-bearer for CRISPR-based therapeutics, going public in 2021 with an upsized $321 million IPO. For years, the company was hailed as a "force of nature" in the gene-editing space, with CEO Rachel Haurwitz, who has led the company since its inception, championing the potential of "chardonnay" (chRDNA) technology to revolutionize cancer care.
However, the path to commercialization proved increasingly difficult. In April 2025, the company attempted to right-size by cutting 32% of its staff and shuttering all preclinical research. At the time, management remained optimistic, focusing their limited resources on their most promising clinical assets.
The strategy failed to satisfy the market. By October 2026, the cash runway concerns reached a breaking point. Following the announcement of the strategic review on October 6, the stock embarked on a three-day descent, nosediving 46% from $1.14 to $0.62. By the close of that week, the shares had withered to $0.46, marking a grim valuation for a firm once pegged as a cornerstone of the next generation of medicine.
The Pipeline Under Fire: Why the Trials Stopped
At the center of the company’s collapse is the forced suspension of its two primary clinical programs: vispacabtagene regedleucel (vispa-cel) and CB-011.
Vispa-cel and the Battle for DLBCL
Vispa-cel was intended to be a first-in-class allogeneic CAR T-cell therapy for relapsed or refractory B-cell non-Hodgkin lymphoma. Utilizing a PD-1 knockout strategy, the therapy was designed to resist the premature exhaustion often seen in T-cells. Despite promising mechanistic foundations, the company struggled to secure the capital necessary to initiate its pivotal Phase III ANTLER-3 trial.
The timing of this struggle could not have been worse. Just one day before Caribou’s announcement, pharmaceutical giants Genmab and AbbVie reported stellar Phase III data for their own therapy, epcoritamab (Epkinly), in a combination regimen. The success of this competitor in the first-line setting has effectively moved the goalposts for allogeneic developers, making the path for a newcomer like vispa-cel appear increasingly narrow and financially risky.
CB-011 and the Multiple Myeloma Hurdle
Simultaneously, Caribou halted its CaMMouflage trial for CB-011, an allogeneic anti-BCMA CAR-T candidate for relapsed/refractory multiple myeloma (RRMM). While the company demonstrated an impressive 92% overall response rate in its early 12-patient cohort, the competitive landscape in the myeloma space is saturated with high-performing autologous therapies like J&J’s Carvykti and Bristol Myers Squibb’s Abecma. The threat of "antigen loss"—where cancer cells mutate to evade the CAR-T treatment—remained a looming technical shadow that investors were unwilling to fund through further clinical cycles.
Supporting Data: A Balance Sheet in Decline
The financial strain is clearly visible in the company’s recent filings. As of June 30, 2026, Caribou reported $113.8 million in cash, cash equivalents, and marketable securities. While this represented a manageable dip from the previous quarter, it marked a 38% slide compared to the $183.9 million held in June 2025.
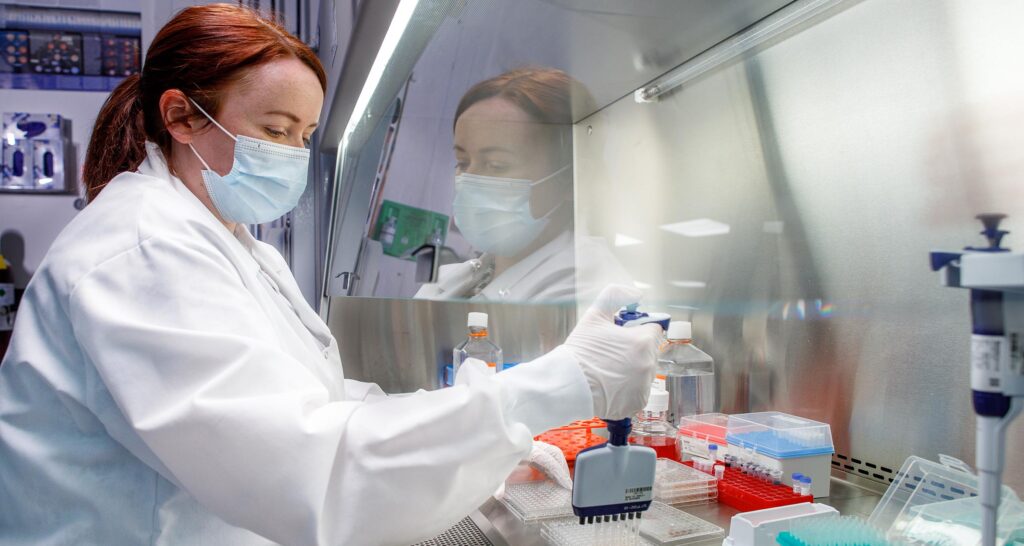
Wall Street analysts, including Leerink Partners’ Daina M. Graybosch, PhD, were quick to highlight the disparity between the company’s capital needs and its market reality. Graybosch, who downgraded the firm from "Outperform" to "Market Perform" and slashed the price target from $4 to $1, noted that investors were largely unwilling to fund the trials under the dilutive terms that would have been required to keep the company afloat.
Official Responses and the "Heartbreaking" Pivot
In a poignant message posted to LinkedIn, CEO Rachel Haurwitz addressed the company’s stakeholders, characterizing the decision as a "heartbreaking turn." She was careful to emphasize that the suspension of trials was not a failure of the science itself, but a concession to the "difficult reality" of the current biotech financing environment.
"This decision is not a loss of belief in our science, our clinical data, or what these programs could mean for patients," Haurwitz stated. "It reflects the difficult reality that the current financing environment for allogeneic CAR T-cell therapies has made it impossible to secure the capital required to responsibly advance them."
Her previous optimism—often centered on the philosophy that "doing right by patients" would eventually translate into business success—has now been tempered by the harsh realities of the capital markets. The company has retained Wedbush Securities as its exclusive financial advisor to explore all options, which could range from a full sale of the company to the licensing of its intellectual property or a complete liquidation of assets.
Broader Implications: The "Allogeneic Winter"
The situation at Caribou serves as a cautionary tale for the broader cell therapy industry. The promise of "off-the-shelf" (allogeneic) CAR-T therapies was that they would be cheaper, faster, and more accessible than the current standard of bespoke (autologous) treatments. However, as developers have found, the biological hurdles—such as graft-versus-host disease and immune rejection—remain significant.
When coupled with a tightening macro-economic environment, where investors are favoring near-term commercial viability over long-term clinical potential, firms like Caribou find themselves in a "valley of death."
The Competitive Squeeze
The rise of bispecific T-cell engagers (TCEs) is further complicating the landscape. These drugs, which are easier to manufacture and distribute than cell therapies, are setting new standards for efficacy in the frontline setting. For an allogeneic CAR-T developer, every incremental delay in a trial represents a massive loss in potential market share.
What Lies Ahead?
For Caribou, the immediate future is shrouded in uncertainty. The company has essentially transitioned from a drug developer to a distressed asset seeking a suitor. While the underlying CRISPR-based intellectual property remains highly valuable—and will undoubtedly be of interest to larger biotech and pharma firms—the dream of a standalone, patient-centric entity built by the pioneers of gene editing is fading.
As the industry watches, the "Caribou story" reminds us that in biotechnology, the bridge between a Nobel-caliber discovery and a patient-ready medicine is not just built on scientific brilliance. It is built on the cold, hard mathematics of venture capital and the ability to outrun the competition before the cash runs dry. For now, the company that once led the CRISPR revolution is fighting to ensure its own survival.