The Biotech Renaissance: A 2026 Sector Analysis and Market Outlook
After four years of post-pandemic stagnation, the biotechnology sector has finally emerged from its winter. As of late 2026, the industry is witnessing a robust revival, characterized by surging ETF performances, a dramatic uptick in initial public offerings (IPOs), and a fundamental shift in how global drug development is financed and executed.
Barring a cataclysmic shift in global markets over the final two months of the year, 2026 will be remembered as the definitive “comeback year” for biotech.
The State of the Market: A Statistical Surge
The recovery is not merely anecdotal; it is reflected in the performance of the industry’s bellwether funds. The iShares Biotechnology ETF (Nasdaq: IBB), the sector’s largest by total assets, has climbed 34% over the 12 months ending in late October, moving from $154.58 to $207.74. Even more impressive is the State Street SPDR S&P Biotech ETF (NYSE Arca: XBI), which has seen a 39% leap, climbing from $107.56 to $149.54.
This renewed investor appetite has catalyzed a massive surge in public market debuts. According to data from the investment bank Locust Walk, 27 IPOs have been completed this year, raising a combined $7.776 billion. This represents a staggering 573% increase over the $1.155 billion raised across 11 offerings throughout the entirety of 2025. The third quarter alone saw nine IPOs hit Wall Street, totaling $2.4 billion—the highest quarterly volume seen in five years.
Chronology of the Rebound: From Stagnation to Momentum
The road to the current 2026 highs was not linear. Following the 2020–2021 boom, the industry endured a grueling period of valuation corrections, high interest rates, and a "risk-off" mentality among venture capitalists.
- Early 2026: Market sentiment began to thaw, driven by the resolution of long-standing valuation gaps and a renewed focus on clinical-stage assets rather than speculative, early-stage platforms.
- Mid-2026: A brief, geopolitical-induced pause in IPO activity occurred following the onset of the Iran conflict. However, the market showed remarkable resilience, heating up again through the summer months.
- Q3 2026: The market saw the most significant IPO activity in half a decade, punctuated by a shift toward Private Investment in Public Equity (PIPE) financing, which emerged as a necessary tool for companies utilizing reverse mergers to reach the public markets.
- Current Outlook: The market is currently holding its breath ahead of the U.S. midterm elections, with investors closely monitoring interest rate trends and inflation prints, both of which remain critical levers for long-dated biotech assets.
The China-U.S. Arbitrage and the Licensing Landscape
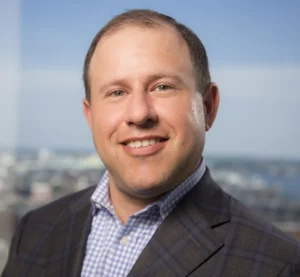
A significant portion of the current deal flow is being driven by the evolving dynamics between U.S. pharma and Chinese biotech firms. Geoff Meyerson, CEO and co-founder of Locust Walk and Banyan BioInnovations, notes that the nature of these cross-border deals is fundamentally different from domestic U.S. transactions.
"In the United States, most licensing deals are early-stage discovery and preclinical," Meyerson explains. "It’s rare to do a clinical-stage license domestically, because typically, if a pharma company wants U.S. rights, they prefer to acquire the entire company. However, the dynamics in China are different."
With the Hong Kong markets facing regulatory headwinds and becoming increasingly difficult for domestic companies to navigate for capital, licensing has become the "lifeblood" of the Chinese biotech ecosystem. While U.S. deals prioritize the net present value of assets, Chinese deals often emphasize total deal value—inflated by milestone payments that may never be triggered—to satisfy optics and provide a path for liquidity that is otherwise unavailable through M&A or public exits.
Supporting Data: Challenges Beneath the Surface
While the headline numbers are positive, the 2026 Q3 Market Conditions Report by Locust Walk reveals a bifurcated reality. While venture financing activity remains stronger than in 2025—with 46 deals in North America compared to 38 in Q3 2025—the focus has shifted away from the "high-science white space" that defined the pandemic era.
The average deal size has grown to $96 million, up from $75 million in the same period last year. Crucially, this capital is increasingly concentrated in Series B rounds and beyond. For startups at the Series A or discovery phase, the "capital winter" is far from over. Investors are demanding that companies remain in academic or early-stage incubation longer, only spinning out when they possess a fully developed candidate or an active IND (Investigational New Drug) application.
Official Perspectives: The Role of AI and Future Risks
A central theme in 2026 has been the integration of Artificial Intelligence into drug discovery. However, industry veterans remain pragmatic. Meyerson argues that while AI is a powerful tool for initial discovery, it does not bypass the fundamental requirements of drug development.
"99.5% of all drug spend happens after you have a lead candidate," Meyerson notes. "AI has an impact, but you still have to put a drug into a human and test it. AI can’t accelerate the course of a disease or the human biological response."
Regarding the entry of massive AI firms like Anthropic into the life sciences space, Meyerson suggests that these companies face a "build or buy" dilemma. To be successful in pharma, they must either evolve into full-fledged drug developers—a move that would likely drag down their rapid growth metrics—or remain as SaaS providers selling tools to the industry.
Furthermore, geopolitical risk looms large. The potential for further restrictions on technology transfers between the U.S. and China is a primary concern for investors. Yet, Meyerson remains balanced: "There is just as much, if not more, risk in the actions of the Chinese government compared to the U.S. government… My instinct is that it’s not going to be something that is going to be shut down. There will always be a way around it."
Implications for 2027 and Beyond
Looking toward 2027, the industry is positioned for a period of stabilization, provided interest rates on long-dated treasuries do not climb further. The "patent cliff" facing major pharmaceutical companies remains a powerful, built-in driver of M&A activity. As large pharma firms lose exclusivity on legacy products, they are forced to buy innovation from the biotech sector, ensuring a constant cycle of demand.
The focus in 2027 will likely remain on the "big three" therapeutic areas: Oncology, Immunology, and CNS (Central Nervous System). Interestingly, rare disease research has seen a relative cooling in receptivity as investors chase the larger market opportunities that pharma is currently prioritizing.
As the industry moves toward the new year, the overarching sentiment is one of cautious optimism. After a four-year period of restructuring, the biotech ecosystem has become more disciplined and more focused on clinical outcomes.
"I don’t believe that we’re only going to have one year of a window and then it shuts down again," Meyerson concludes. "I think the industry is too large and too robust for that to happen."
For investors and developers alike, the message is clear: the era of speculative, high-science platform funding is being replaced by an era of clinical validation, strategic cross-border partnerships, and a focus on assets that can demonstrate tangible value in human patients. The 2026 recovery is not merely a market correction—it is the maturation of a sector that is once again ready to lead the global healthcare economy.